|
|
|
|
|
| October 15, 2026 |
|
Insurers say they’re starting to write new California homeowner policies 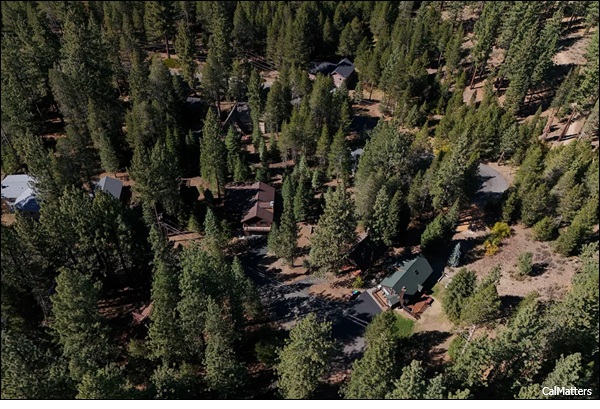
SACRAMENTO - Insurance companies are starting to write new policies in California again after years of holding back as wildfire risk climbed higher.
The state Insurance Department says that means outgoing Commissioner Ricardo Lara’s new regulations, intended to boost insurance availability, are working. Each time a company declares its plans to sell policies again, the department touts it as a win. But the state has not released the number of new policies the companies have written so far. Enter Consumer Watchdog, the advocacy group that often butts heads with the department. It released an estimate of new policy commitments: 12,189 since January 2025, when Lara’s so-called sustainable insurance strategy went into effect. The strategy allows insurers to use catastrophe modeling, which they say more adequately takes risk into account because it includes forward-looking models, and to factor in reinsurance costs when setting their rates. The new rules allow insurers to factor in catastrophe models and their reinsurance costs as long as they commit to increasing sales in high-risk areas. Of the 10 companies that requested rate increases under the new rules, only five have committed to selling more policies, the group’s analysis shows. The regulations call for insurance companies to choose one of these options: Write 85% of their market share in high-risk areas; grow their policies 5% in such areas; or increase their number of policies 5% by taking customers out of the FAIR Plan. Some of the companies that have requested or secured rate increases claim they already meet the 85% threshold. The state has seen its deadliest and most destructive fires in the past decade. Several years ago, insurance companies started complaining that California, which has authority over premium increases, was not approving them quickly enough to allow insurers to match their rates to the growing risk of climate change and wildfires. Some companies stopped writing new policies, or decided not to renew existing ones. Lara’s new regulations — which include provisions championed by the insurance industry — aim to address the issue. Property owners turn to the state-mandated, insurance-run alliance when they can’t buy policies elsewhere, so the higher the number of policies in the plan, the poorer the health of the main insurance market. As of June, the FAIR Plan still had about 697,000 active policies, up 157% since September 2022. California’s average home insurance costs have risen 5% so far this year, one of the biggest increases in the nation, according to insurance-comparison site Insurify. More than 8 million homeowners in the state have insurance policies, according to the insurance department. (Source: CalMatters) Story Date: October 12, 2026
|
    |
